Branch Manager · NMLS 162239
Your Utah Home Starts With a Clear Plan.
Whether you're buying in Kaysville, settling into Washington City, or refinancing anywhere in between, Jennifer Reich helps you understand your options and choose with confidence.
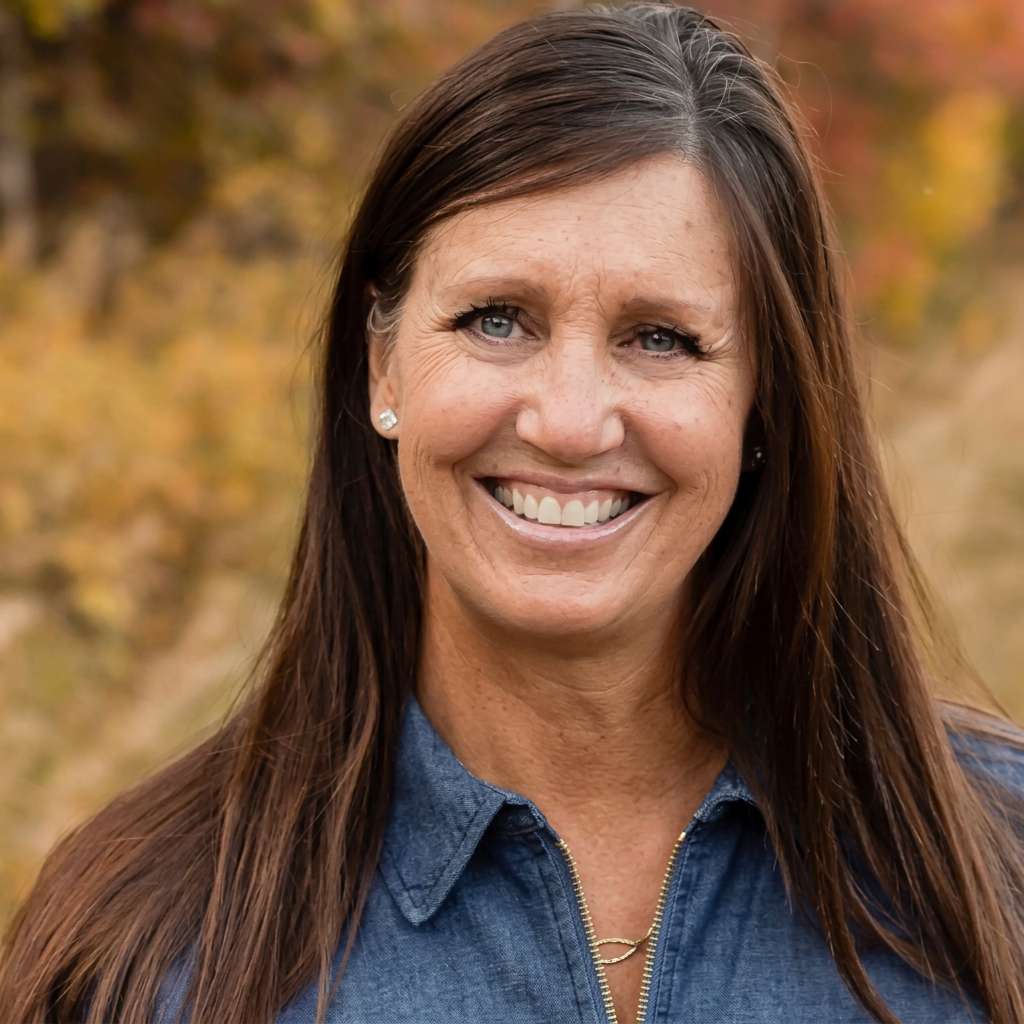
Jennifer Reich
A personal approach
Clear explanations. Honest guidance. Real communication.
As a Branch Manager with Fairway in Kaysville, Jennifer works directly with buyers and homeowners to compare loan options side by side — payment, cash to close, and long-term cost — so every decision is an informed one.
Meet JenniferIn their own words
Real people. Personal guidance.
“Jenn was quick to respond to all my questions. She is easy to communicate with and made the entire process run smooth. Can't say enough great things about Jenn!”
Jessica G · Harrisville, UT
· Experience.com
“Jenn is wonderful to work with. She took the time to explain several loan options, provided timely updates, and made the entire process easy to navigate,”
Cynthia B · Mapleton, UT
· Experience.com
“Jenn was always available to answer questions and help in any way she could. We had an unconventional situation and she helped so much getting us through it.”
Tesse H · Ferron, UT
· Experience.com
Selected public reviews from Experience.com. Individual experiences vary and do not guarantee loan approval or particular results.
The Fairway way
Our Core Values
At Fairway, how we do things matters just as much as what we do. Our core values guide how we work, connect with people, and serve our communities.
Primary focus
Conventional Loans
The most common path to financing a Utah home — flexible across primary homes, second homes, and investment properties.
Explore Your Loan Options- Usable for primary homes, eligible second homes, and investment properties
- Low down payment options for eligible primary-residence buyers
- PMI can generally be removed once enough equity is reached
- Wide range of terms, including fixed and adjustable options
FHA Loans
Mortgage insurance backed by the Federal Housing Administration can open doors for buyers with smaller down payments.
Learn moreVA Loans
A home loan benefit earned through service, guaranteed by the U.S. Department of Veterans Affairs.
Learn moreNon-QM Loans
Alternative ways to qualify when your finances don't fit standard mortgage documentation.
Learn moreAreas served
From the Wasatch Front to red rock country
Based in Kaysville and serving borrowers across Davis County and Washington County.
How it works
A simple path from first question to closing
- 1
Conversation
Share your goals. Jennifer listens and explains your options in plain language.
- 2
Preapproval
Review credit, income, and assets so you know where you stand.
- 3
Find your home
Shop with confidence and a clear budget.
- 4
Application & underwriting
Submit documents securely; Jennifer keeps you updated.
- 5
Closing
Review your final numbers, sign, and get your keys.
Homebuyer resources
Guides worth reading
Conventional vs. FHA Loans: How to Compare
A side-by-side look at conventional and FHA mortgages — down payment, mortgage insurance, credit, and occupancy — to help you choose.
Understanding VA Home Loan Eligibility
Who qualifies for a VA loan, how the Certificate of Eligibility and entitlement work, and what to know about the funding fee.
Preparing for Mortgage Preapproval
What a preapproval is, what documents to gather, and how to avoid surprises before you start making offers.
FAQs
Common questions
What's the difference between prequalification and preapproval?
Prequalification is an early estimate based on information you share. Preapproval goes further: your credit is reviewed and income and assets are documented, so sellers can see you've taken a real step toward financing. Neither is a final loan approval.
How much do I need for a down payment?
It depends on the loan. Some conventional programs allow as little as 3% for eligible primary-residence buyers, FHA allows 3.5% for qualified borrowers, and VA may allow zero down for eligible borrowers. Second homes and investment properties usually require more. Jennifer can compare options for your situation.
What are closing costs?
Closing costs are fees for services needed to complete your loan and purchase — such as lender fees, appraisal, title insurance, and recording — plus prepaid items like property taxes and homeowners insurance. Your Loan Estimate itemizes them.
Does Jennifer offer the lowest rate?
No one can honestly promise the lowest rate. Rates depend on the market, your credit, the loan type, and other factors. What Jennifer can promise is a clear explanation of your options and costs so you can compare with confidence.
How long does it take to close a mortgage?
Timelines vary based on the loan, the property, appraisal scheduling, and how quickly documents come in. Jennifer will give you a realistic expectation for your loan and keep you updated along the way.
Ready to talk about your next step?
Tell Jennifer what you're working toward. She'll explain your options in plain language and help you decide what comes next.